
I remember standing at the window of a friend's 23rd-floor HDB flat in Tampines, watching the sun bleed orange across the reservoir below. The flat was enormous — three bedrooms, a proper kitchen, a living room big enough to host twelve people for Chinese New Year. My friend had paid about S$450,000 for it.
A week later, I visited another friend in a condo near Orchard Road. Her unit was half the size but came with an infinity pool, a gym that would embarrass most commercial chains, and a concierge who remembered her dog's name. Her mortgage? More than double.
That contrast captures the heart of Singapore's most debated housing question: condo or HDB? It's a question that touches everything — your finances, your commute, your weekends, even the way you raise your children. And after living in Singapore for years, talking to dozens of homeowners on both sides, and crunching the numbers more times than I care to admit, I've come to believe there's no universally right answer. But there is a right answer for you, and this guide will help you find it.
Understanding Singapore's Two Housing Worlds
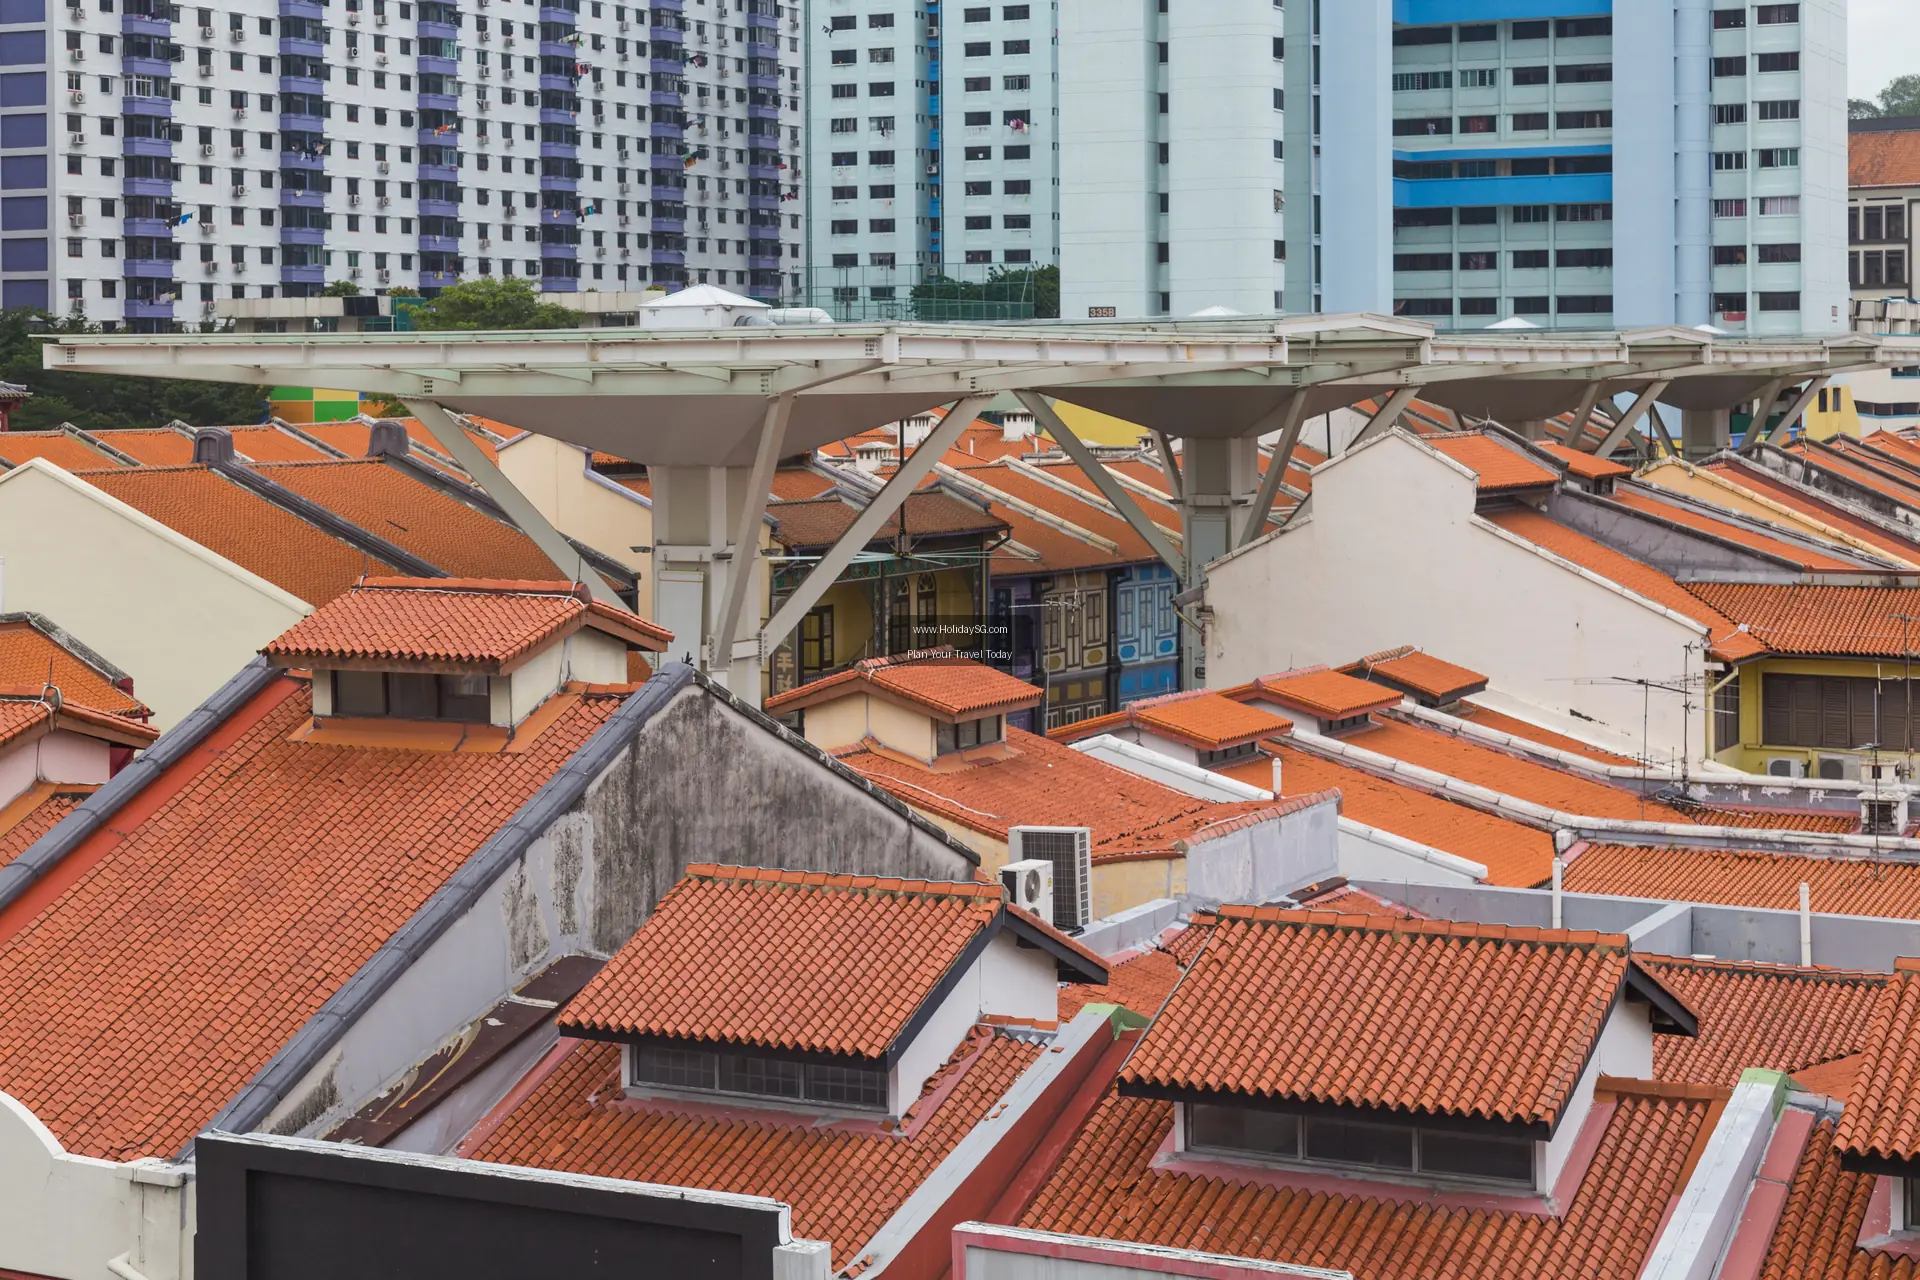
Singapore is one of the few countries on Earth where public housing isn't synonymous with "budget option." The Housing Development Board (HDB) has built over one million flats since independence, and today roughly 80% of Singapore's resident population lives in one. These aren't crumbling tower blocks — many are architecturally striking, well-maintained, and located within walking distance of MRT stations, hawker centres, and schools.
Condominiums, on the other hand, represent Singapore's private residential market. They come with facilities that HDB estates simply cannot match — swimming pools, tennis courts, barbecue pits, function rooms, 24-hour security. But they also come with a price tag that makes first-time buyers inhale sharply.
Before we dive into the comparison, it's worth noting something that often gets lost in the debate: Singapore is a remarkably small country. Whether you live in a Punggol HDB or a Bukit Timah condo, almost everything — from visa services to world-class attractions — is accessible within 30 to 45 minutes. The real differences lie elsewhere.
The Price Gap: What You're Actually Paying For
Let's start with what matters most to nearly everyone: money. The price difference between HDB flats and condominiums isn't just significant — it's structural, and it affects your financial life for decades.
| Cost Category | HDB (4-Room Resale) | Condo (2-Bedroom) |
|---|---|---|
| Purchase Price (2026) | S$500,000–S$750,000 | S$1,200,000–S$2,000,000 |
| Monthly Mortgage (25-yr, 3%) | S$2,100–S$3,200 | S$5,100–S$8,500 |
| Monthly Maintenance | S$60–S$90 | S$350–S$800 |
| Property Tax (Annual) | S$0–S$500 | S$2,000–S$6,000 |
| Stamp Duty (Citizen, 1st property) | S$9,600–S$17,100 | S$28,600–S$54,600 |
| Total First-Year Cost | ~S$36,000–S$56,000 | ~S$92,000–S$165,000 |
That table tells a blunt story. For many Singaporean couples, the question isn't really "condo or HDB?" — it's "can we afford a condo at all?" And the honest answer, for a household earning the median income of about S$10,000 per month, is usually no. At least not without stretching finances uncomfortably thin.
But here's what the table doesn't show: HDB buyers get access to CPF housing grants (up to S$80,000 for eligible first-timers) and concessionary HDB loan rates (currently 2.6%). Condo buyers don't get any of that. They're borrowing at commercial rates, which in 2026 hover around 3.0–3.5%.
Space: The Metric Nobody Talks About Properly
People love quoting square footage when comparing HDB and condo. But the numbers alone are misleading unless you understand what they actually feel like to live in.
| Unit Type | Typical Size (sq ft) | Bedrooms | Price per sq ft |
|---|---|---|---|
| HDB 3-Room | 700–750 | 2 | S$500–S$700 |
| HDB 4-Room | 900–1,000 | 3 | S$550–S$750 |
| HDB 5-Room | 1,100–1,200 | 3–4 | S$500–S$650 |
| Condo 1-Bedroom | 450–550 | 1 | S$1,800–S$2,500 |
| Condo 2-Bedroom | 650–800 | 2 | S$1,600–S$2,200 |
| Condo 3-Bedroom | 1,000–1,200 | 3 | S$1,500–S$2,000 |
A 4-room HDB flat gives you roughly the same floor area as a 3-bedroom condo — but at one-third the price per square foot. And that HDB flat typically has a proper separate kitchen, a utility room for laundry, and corridors wide enough for a child on a scooter. Many new condos, by contrast, sacrifice corridor space for open-concept layouts that look gorgeous in showflat photographs but feel cramped the moment you fill them with actual furniture and actual children.
I once measured the master bedroom in a friend's S$1.8 million condo. It was 11 feet by 10 feet — barely enough for a queen bed, two nightstands, and a wardrobe. His HDB-dwelling colleague had a master bedroom nearly 40% larger.
Facilities and Lifestyle: Where Condos Pull Ahead
This is where the condo argument gets genuinely compelling. Step outside your front door in a condo and you might walk past a lap pool, a children's play area, a tennis court, a landscaped garden with a reading pavilion, and a well-equipped gym — all without leaving your compound.
HDB estates have improved massively over the years. Newer BTO developments like those in Tengah and Bidadari include covered walkways, community gardens, rooftop terraces, and precinct pavilions. But they still can't match the private exclusivity of a condo's facilities.
| Facility | HDB | Condo |
|---|---|---|
| Swimming Pool | Public pools nearby (S$1–S$2) | On-site, included |
| Gym | ActiveSG (S$2.50/entry) | On-site, included |
| Security | Police patrols, CCTV | 24/7 guards, access cards |
| Parking | Season parking ~S$110/month | Usually 1 lot included |
| BBQ Pit | Shared, book through RC | On-site, often multiple |
| Children's Playground | Public playground at void deck | Dedicated play zones |
Here's the thing though: you're paying for those facilities whether you use them or not. That S$350–S$800 monthly maintenance fee doesn't go away if you never touch the pool. I know a condo resident who swims exactly zero times a year — she's essentially paying S$6,000 annually for a pool she looks at through her window.
On the other hand, HDB residents who want similar facilities can join gyms (S$50–S$100/month), swim at public pools (S$1.50 per visit), and book community centre function rooms for gatherings. The cost is lower, but the convenience isn't there in the same way.
Location and Connectivity
One of HDB's greatest strengths is its integration with Singapore's transport infrastructure. Most HDB estates are built around MRT stations, bus interchanges, and neighbourhood centres. Newer towns like Punggol and Tengah were master-planned with connectivity as a first principle.
Condos, particularly newer ones, tend to cluster in less central locations unless you're paying a premium for District 9 or 10 (Orchard, River Valley, Tanglin). A condo in Sengkang or Pasir Ris might be a 15-minute walk from the nearest MRT, whereas the HDB next door is two minutes away.
This matters more than you'd think. In a country where weekend activities like visiting Night Safari (from S$38.53) or taking the family to Wild Wild Wet (from S$17.09) are part of the rhythm of life, being close to public transport saves both time and taxi fares.
The Investment Angle: Appreciation and Rental Yield
Singaporeans love talking about property as an investment. And the data tells an interesting story that doesn't always favour the option you'd expect.
| Investment Metric | HDB | Condo |
|---|---|---|
| 5-Year Capital Appreciation (avg) | 20–35% | 15–30% |
| Gross Rental Yield | 4–5% | 2.5–3.5% |
| Minimum Occupation Period | 5 years | None (resale) |
| Rental Eligibility | After MOP, max 6 pax | No restrictions |
| Lease Decay Risk | High (99-year only) | Moderate (freehold options exist) |
Surprised? Many people are. HDB flats in mature estates — Toa Payoh, Queenstown, Tiong Bahru, Bishan — have appreciated phenomenally. A 5-room flat in Queenstown that cost S$300,000 in 2015 might fetch S$700,000 today. On a percentage basis, that's hard for most condos to match, especially when you factor in the lower entry cost.
However, condos offer flexibility that HDB flats simply cannot. There's no Minimum Occupation Period for resale condos, freehold options eliminate lease decay anxiety, and you can rent the entire unit to anyone without the occupancy restrictions HDB imposes. For property investors, that flexibility has real value.
Who Can Buy What: Eligibility Rules
This is where Singapore's housing market gets uniquely complex. Not everyone can buy both options, and the rules vary depending on your citizenship, marital status, and age.
| Buyer Profile | HDB (New BTO) | HDB (Resale) | Condo |
|---|---|---|---|
| SC + SC Couple | Yes | Yes | Yes |
| SC + PR Couple | Yes | Yes | Yes (5% ABSD for PR) |
| PR + PR Couple | No | After 3 years PR | Yes (5% ABSD each) |
| Foreigner | No | No | Yes (60% ABSD) |
| Single SC (35+) | 2-room Flexi only | Up to 5-room | Yes |
For foreigners and expatriates — many of whom are in Singapore on employment passes — condominiums are often the only option for ownership. If you're visiting Singapore and considering whether to put down roots, you may want to check the visa requirements and understand how your residency status affects housing eligibility before making plans.
The Community Factor: Kampung Spirit vs Private Seclusion
There's something about HDB living that's hard to quantify in a spreadsheet. The void deck where uncles play chess. The corridor where your neighbour leaves a plate of kueh for you during Hari Raya. The kopitiam downstairs where the aunty knows your regular order. This is the kampung spirit — the communal warmth — that defines HDB life for many Singaporeans.
Condo living trades that community warmth for privacy and curated social spaces. You might know your immediate neighbours by sight, but the transient nature of many condo populations — rental turnover, foreign residents coming and going — means relationships tend to be more surface-level. The trade-off is genuine: you get more personal space, less noise from neighbours, and a controlled environment. Some people find that liberating. Others find it lonely.
I've noticed that families with young children often start in condos for the facilities but eventually move to HDB estates when they want their kids to grow up with a stronger sense of neighbourhood and community. Meanwhile, couples without children and working professionals often do the reverse — starting in HDB and upgrading to a condo when they can afford it.
Renovations: Freedom and Constraints
HDB flats offer more renovation freedom than many people realise. You can hack walls (non-structural ones, with HDB approval), install built-in wardrobes, redo the entire kitchen, and essentially reshape your home. The renovation industry in Singapore is dominated by HDB projects, and a typical 4-room flat renovation costs S$30,000–S$60,000.
Condos have stricter renovation rules governed by the MCST (Management Corporation Strata Title). Wet works, hacking, and structural changes usually need MCST approval. Renovation hours are restricted, and some condos limit the duration of renovation works to three months. Costs are similar or higher, partly because contractors charge more for condo jobs (access restrictions, material handling through lobbies, and tighter timelines).
Renting Out: Rules and Returns
If you're considering buying property partly as an investment, the rental rules differ significantly.
| Rental Factor | HDB | Condo |
|---|---|---|
| Whole-unit rental allowed? | After MOP (5 years) | Anytime |
| Room rental allowed? | After MOP, owner must live in | Yes, no restrictions |
| Minimum rental period | 6 months | 3 months (some 6) |
| Max occupancy cap | 6 persons (non-related) | No cap (check MCST rules) |
| Tenant nationality restrictions | SC/PR/approved passes | None |
HDB rental yields are actually higher on a percentage basis (4–5% vs 2.5–3.5% for condos), mainly because the purchase price is so much lower. But the restrictions — MOP, occupancy caps, nationality rules — make HDB rental less flexible. Condos are easier to rent out and attract a wider pool of tenants, including expatriates on corporate housing budgets.
Living Near Singapore's Best Experiences
One of the underappreciated joys of living in Singapore — whether in an HDB or a condo — is how accessible the island's attractions are. On any given Saturday, you could be watching the sunset from the Singapore Flyer (from S$28.00), exploring the ArtScience Museum (from S$18.00), or watching the spectacular Wings of Time show on Sentosa (from S$18.70).
Families in HDB estates near Pasir Ris or Woodlands might be slightly closer to attractions like Wild Wild Wet (from S$17.09) or the Mandai wildlife parks. Meanwhile, condo residents in the southern and central corridors have quicker access to Sentosa, where you can spend a day at Skyline Luge (from S$35.51) or test your courage at Mega Adventure Park (from S$59.00).
The point is, your housing type doesn't limit your access to what makes Singapore special. It just changes how you get there and how much you spend on transport getting to it.
The Emotional Side: What Nobody Puts in the Brochure
Let me tell you about two conversations I had in the same week last year.
The first was with a couple who'd just upgraded from a 5-room HDB in Clementi to a condo in the same neighbourhood. "We love the pool and the privacy," the wife told me. "But I miss walking to the wet market and chatting with the vegetable aunty. The condo has a minimart, but it's not the same."
The second was with a young professional who'd moved from a condo in Tanjong Pagar to a resale HDB in Tiong Bahru. "My condo friends thought I was crazy," he said. "But I wanted to be in a real neighbourhood — with the Tiong Bahru market, the old bookshop, the cat that sits outside the bakery. I don't need a pool I use twice a year."
These stories aren't unusual. Housing isn't just about square footage and capital appreciation. It's about how you want to live — how your mornings feel, what you see when you open your curtains, whether your children play in corridors or curated gardens.
Financial Planning: A Realistic 10-Year Model
Let's run the numbers over a decade for a Singaporean couple, both citizens, buying their first property. We'll compare a 4-room HDB resale in a mature estate with a 2-bedroom condo in the OCR (Outside Central Region).
| 10-Year Financial Summary | HDB 4-Room (S$600k) | Condo 2-Bed (S$1.4M) |
|---|---|---|
| Total Mortgage Paid (10 yrs) | S$310,000 | S$740,000 |
| Total Maintenance (10 yrs) | S$9,000 | S$66,000 |
| Total Property Tax (10 yrs) | S$3,000 | S$35,000 |
| Estimated Appreciation | +S$180,000 (30%) | +S$280,000 (20%) |
| Net Position After 10 Years | +S$180k gain, S$322k spent | +S$280k gain, S$841k spent |
The HDB buyer spends S$322,000 over a decade and gains S$180,000 in equity. The condo buyer spends S$841,000 and gains S$280,000. That S$519,000 difference in total spending buys a lot of experiences. It buys family holidays, education funds, weekend adventures, and financial peace of mind.
To put it in perspective: the savings from choosing HDB over condo for ten years could fund more than 7,000 trips to Universal Studios Singapore (from S$65.43). Not that you'd go 7,000 times, but the point is clear.
For Expats: The Practical Realities
If you're an expatriate on an Employment Pass or S Pass, your housing decision is shaped by different forces. You can't buy an HDB flat (unless married to a Singaporean citizen), so if you're renting, the choice is really about which type of rental fits your situation.
Renting an HDB room costs S$800–S$1,500 per month. Renting an entire HDB flat runs S$2,000–S$3,500. A condo rental is S$3,000–S$6,000+ for the same number of bedrooms. If your company provides a housing allowance, a condo may be fully covered. If you're paying out of pocket, HDB is the financially sensible choice — and the savings let you explore Singapore more freely.
If you're planning a trip to Singapore to scout housing, you might also want to book a flight reservation for your visa application — we offer a flight reservation service to help with the paperwork.
Making the Most of Weekend Life in Singapore
Whichever housing type you choose, Singapore rewards those who get out and explore. The island packs an extraordinary density of experiences into 733 square kilometres. A typical weekend for a family might include catching the Madame Tussauds wax museum (from S$30.59) on Saturday morning, then heading to the National Gallery (from S$13.00) in the afternoon.
Sunday might mean a morning at Singapore Cable Car (from S$31.50) followed by lunch at a hawker centre — where a plate of chicken rice costs S$4 and tastes better than most S$30 restaurant versions.
HDB residents often have the advantage here: many HDB estates are built adjacent to neighbourhood hawker centres, wet markets, and community clubs. Condo residents might need to drive or take a bus to access the same everyday amenities. But condo residents counter with the convenience of their on-site facilities — a quick swim before dinner, a gym session at 6 AM without leaving the compound.
Schools, Children, and the Education Factor
For families with school-age children, housing type can directly affect educational options. Singapore's primary school registration system gives priority based on distance from the school — specifically, within a 1-kilometre and 2-kilometre radius. Many of Singapore's most sought-after primary schools are located in mature HDB estates: Tao Nan School in Marine Parade, Nanyang Primary in Bukit Timah, Raffles Girls' Primary in Toa Payoh.
Condos in the same zones exist, of course, but they're typically much more expensive. A 3-bedroom condo within 1 km of Nanyang Primary might cost S$2.5 million or more. A 5-room HDB resale in the same radius could be S$800,000–S$1,000,000. Both get the same distance priority for school registration.
There's also a softer benefit to raising children in HDB estates. Kids grow up playing in void decks and common corridors with neighbours' children, developing social skills that are harder to cultivate in the more insular environment of a condo compound. Several parents I've spoken with specifically chose HDB for this reason — they wanted their children to grow up understanding how most Singaporeans actually live.
That said, condo playgrounds and swimming pools are undeniably attractive for families. There's something to be said for being able to take your toddler for a swim at 6 PM on a Wednesday without leaving your building. And the controlled, gated environment gives some parents peace of mind about safety — even though Singapore is one of the safest countries in the world regardless of where you live.
The Lease Decay Question
This deserves its own section because it's increasingly important and often misunderstood. All HDB flats are 99-year leasehold. Some condos are freehold, but many are also 99-year leasehold.
Here's why this matters: a 99-year lease HDB flat in a mature estate might be 30–40 years old. That means 60–70 years of remaining lease. Banks will lend for up to age 65, and they're increasingly cautious about flats with less than 60 years of lease remaining. An old HDB flat with 50 years left may be hard to sell at a good price because the buyer's financing options narrow.
Freehold condos don't have this problem. And while 99-year leasehold condos face the same theoretical decay, their en-bloc (collective sale) potential provides an exit valve that HDB flats rarely have.
Best Neighbourhoods for Each Housing Type
If you've decided on one type, the next question is where. Here are some neighbourhood recommendations based on common priorities.
Best HDB Estates for Families: Punggol (newest infrastructure), Tampines (complete town centre), Bishan (central, near schools), Woodlands (upcoming RTS to JB)
Best HDB Estates for Value: Sengkang (large flats, affordable), Yishun (improving rapidly), Jurong East (upcoming transformation)
Best Condo Areas for Professionals: Tanjong Pagar (CBD-adjacent), Tiong Bahru (lifestyle), Bugis-Lavender (trendy, accessible)
Best Condo Areas for Families: Bukit Timah (top schools), East Coast (beach lifestyle), Clementi-West Coast (university town vibe)
The Hybrid Strategy: Start HDB, Upgrade Later
Many savvy Singaporeans adopt a two-step approach that leverages the strengths of both housing types.
Step 1: Buy a BTO flat in a good location using CPF grants and the concessionary loan. Live in it for 5 years (the MOP). During this time, save aggressively — the lower monthly costs compared to a condo mortgage let you build a war chest.
Step 2: Sell the HDB at a profit (especially if it's in a mature estate that has appreciated). Use the proceeds plus your savings for a downpayment on a condo. Keep the HDB proceeds in your CPF or invest them.
This strategy has produced more millionaires in Singapore than most people realise. A couple who bought a BTO in Queenstown for S$350,000 in 2016 could sell it for S$700,000+ in 2026, netting S$350,000+ in profit after repaying their CPF — enough for a 25% downpayment on a S$1.4 million condo.
The risk? Property markets don't always go up, and timing matters. But historically, Singapore's housing market has been one of the most resilient in Asia.
Practical Tips for First-Time Buyers
Whether you're leaning toward HDB or condo, these tips apply universally.
1. Never stretch beyond 30% of your income for housing. The Total Debt Servicing Ratio (TDSR) caps your monthly loan repayment at 55% of gross income, but just because the bank will lend you that much doesn't mean you should borrow it.
2. Visit at different times of day. That quiet estate at 2 PM might be deafening at 7 PM. That sunny condo might be permanently in shadow by 4 PM. Walk the neighbourhood in the morning, afternoon, and evening before committing.
3. Talk to the neighbours. They'll tell you things no property agent will — noise issues, flooding, pest problems, MCST management quality.
4. Factor in lifestyle costs. Cheaper housing means more money for experiences — weekend trips to the Singapore Zoo (from S$32.15), evenings watching the Sampan Rides at Marina Bay Sands (from S$11.00), or exploring the Museum of Ice Cream (from S$39.98).
5. Don't buy based on status. I've seen too many people stretch for a condo address they can't comfortably afford. An HDB with money left over for living is better than a condo that leaves you house-rich and cash-poor.
The Daily Life Test
Forget the financial models for a moment. Close your eyes and picture your ideal Tuesday morning. Not Saturday — Tuesday. The routine, unremarkable mornings that make up most of your life.
In an HDB flat, your Tuesday morning might go like this: wake up, make coffee in your spacious kitchen, walk two minutes to the hawker centre downstairs for a S$1.20 kopi and S$3 nasi lemak, then head to the MRT station that's a covered-walkway stroll away.
In a condo, your Tuesday morning might be: wake up, do a quick gym session in the building, swim a few laps, shower, grab a latte from the cafe in the lobby, and drive or Grab to work because the MRT is a 12-minute walk in the heat.
Neither is objectively better. But one of them will resonate with you more than the other. That resonance is your answer.
Frequently Asked Questions
Is an HDB flat a good investment in 2026?
HDB flats in mature estates have shown consistent appreciation of 20–35% over five years. However, lease decay is a real concern for older flats. Focus on flats with 70+ years of remaining lease in well-connected areas for the best investment outlook.
Can foreigners buy HDB flats in Singapore?
No. Only Singapore Citizens and Permanent Residents (after 3 years of PR status) can purchase HDB flats. Foreigners can only purchase private condominiums, subject to Additional Buyer's Stamp Duty (ABSD) of 60%.
What is the Minimum Occupation Period for HDB?
Five years. During this period, you cannot sell the flat or rent out the entire unit. You can rent out rooms after the MOP if you continue to live in the flat.
Are condo maintenance fees worth it?
That depends on your usage. If you swim regularly, use the gym daily, and value 24/7 security, the S$350–S$800 per month delivers genuine value. If you rarely use the facilities, you're paying for amenities you look at but don't touch.
Which appreciates faster — HDB or condo?
On a percentage basis, well-located HDB flats have outperformed many condos in recent years. On an absolute dollar basis, condos typically appreciate more per unit. The right metric depends on whether you're optimising for return on investment (favour HDB) or absolute wealth accumulation (favour condo).
Can I use CPF to buy a condo?
Yes, you can use CPF Ordinary Account funds for a condo purchase, but without the CPF Housing Grant that HDB buyers receive. The Valuation Limit also applies — you can only use CPF up to the lower of the purchase price or the valuation.
The Bottom Line
After all the tables, numbers, and comparisons, here's what it comes down to: HDB flats offer more space, lower costs, better community integration, and surprisingly strong investment returns. Condos offer facilities, privacy, flexibility, and a lifestyle that many find worth the premium.
If you're a young couple starting out, an HDB flat is almost always the smarter financial move. The CPF grants alone can be worth tens of thousands of dollars, and the lower monthly costs give you room to breathe, save, and enjoy life — including all the experiences Singapore has to offer, from Skyline Luge on Sentosa (from S$35.51) to a Sampan ride at Marina Bay (from S$11.00).
If you're a dual-income couple with no children, or an expatriate with a housing allowance, a condo might align better with how you actually want to live day to day.
And if you're someone who likes to hedge? Buy the HDB first, let it appreciate, and upgrade to the condo later with a war chest of equity behind you.
There's one more thing worth mentioning, something that rarely appears in property guides but matters enormously in practice: the psychology of contentment. I've met HDB owners who feel quietly triumphant about their financial discipline — they own their home outright at 45, have a healthy CPF balance, and spend freely on travel and experiences. I've also met condo owners who love coming home to their rooftop garden and wouldn't trade it for anything, even if their mortgage won't be paid off until they're 60. Neither group is wrong. They've simply made different trade-offs about what brings them satisfaction.
Singapore is a country that rewards smart planning and punishes impulsive decisions, especially when it comes to property. Take your time. Visit open houses. Run the numbers with a mortgage calculator. Talk to people who live in both types. And when you finally sign on that dotted line, do it with the confidence that you chose what's right for your life — not someone else's idea of success.
Whatever you choose, remember: the best home in Singapore isn't the one that looks good on paper or impresses your colleagues. It's the one that lets you sleep well — both because you love being there, and because the mortgage isn't keeping you up at night.